The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Caravan loans are a fantastic way for Australians to finance their dream of owning a mobile home on wheels. They offer the convenience of spreading the cost of a caravan over time, making it more affordable for those who may not have the funds to buy one outright.
These loans are popular because they allow families and adventurers alike to explore the great outdoors of Australia with peace of mind, knowing they have secured financing that suits their budget.
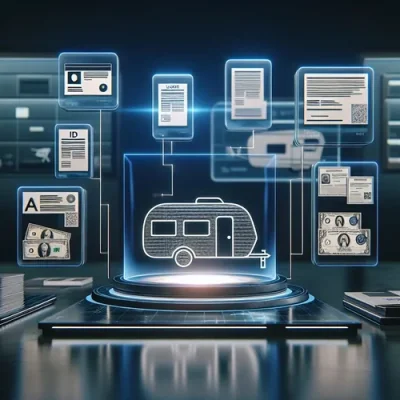
Understanding the requirements set by lenders is crucial before diving into a loan application. Being equipped with the right documents can not only speed up the application process but also increase your chances of approval.
A well-prepared application allows lenders to assess your financial profile quickly and easily, which can result in a smoother, stress-free experience for you. Knowing what you need ahead of time, and having it organised, can make all the difference when applying for a caravan loan.
Identifying Your Lender's Requirements
When it comes to applying for a caravan loan, understanding what each lender requires can make your experience significantly smoother. Different lenders may have varying expectations and criteria for approving loans, so it's crucial to do your homework beforehand.
Start by researching potential lenders to get a sense of what documents they typically request. This might include proof of income, credit reports, and details about the caravan you're planning to purchase.
Understanding these variations can help you tailor your application for each specific lender. Some may have stricter income requirements, while others might focus more on credit history or the type of caravan you want to buy.
By contacting lenders directly and asking for a pre-application checklist, you can gather all necessary documents ahead of time. This proactive approach can help you ensure that you meet all their requirements and increase the likelihood of your application being approved quickly.
Personal Identification Documents
Providing valid identification is a fundamental step in applying for a caravan loan. Lenders use ID to verify your identity, confirm your residential address, and ensure that all the information on your application matches official records. This process is crucial for both legal and security reasons.
Commonly accepted forms of identification include a driver's license, passport, or a birth certificate. A driver's license is typically the most convenient option since it also serves as proof of address. If you don't have a driver's license, a passport or a Medicare card combined with a utility bill can be used to prove your identity and address.
Before you start your application, double-check that your ID is current and not expired. If your driver's license or passport is near its expiration date, it’s wise to renew it to avoid any complications. Keeping your documents up-to-date can help prevent delays in the application process and ensure a smooth transaction.
By ensuring that your identification is accepted and valid, you bolster your chances of securing a loan efficiently and make a professional impression on the lender. This attention to detail can also save time if additional documentation is required after submitting your application.
Proof of Income
Income verification is an essential part of the caravan loan application process. Lenders require proof of income to assess your ability to make loan repayments. This helps them ensure that you can afford to pay back the loan without financial strain.
There are several types of documents you can present to prove your income. For most employed applicants, recent payslips and bank statements are typically sufficient. Payslips provide a detailed record of your salary, including any deductions and net pay.
For those who are self-employed, proving income might require a bit more effort. Lenders may ask for tax returns, profit and loss statements, or business bank statements. These documents help establish a consistent income pattern and validate your self-employment status.
It's important to gather and organize these documents carefully before submitting your application. Ensuring all necessary paperwork is up-to-date and accurate will help streamline the application process and improve your chances of securing the loan.
Credit History and Score
Your credit history and score play a pivotal role in the caravan loan application process. Lenders use your credit score to gauge your financial reliability and repayment habits, making it a key factor in their decision-making process.
A good credit score not only increases your chances of getting approved but can also secure you better loan terms, like lower interest rates. Therefore, keeping track of your credit status is essential when considering a loan.
To review your credit report, you can request a free copy from major credit reporting agencies in Australia, such as Equifax, Experian, or illion. Reviewing your report helps identify any discrepancies or outdated information that might negatively impact your score.
If you find errors, take steps to correct them by contacting the credit agency with supporting documents to rectify the issue. Additionally, you can work on improving your score by ensuring timely bill payments and reducing outstanding debts.
Consistent financial habits, such as maintaining low credit card balances and not opening too many new credit accounts at once, can gradually enhance your credit score. By proactively managing your credit, you'll be in a stronger position to apply for a caravan loan with favourable terms.
Proof of Residence
When applying for a caravan loan, proof of residence is a key requirement that helps lenders confirm your living situation and address. Accurate address verification ensures there's a clear line of communication and supports the legitimacy of your application.
Caravan Loans Australia Weekly News Wrap
 This week: the RBAs 3 November hike to about 4.85% keeps pressure on personal loan costs; November snapshots show lowest unsecured rates near six per cent but outcomes vary by profile; ASIC flags new imposter and unlicensed scams—double‑check web addresses and verify businesses before paying; and rising savings rates can boost your caravan deposit if you meet account conditions. Practical takeaways: compare using comparison rates and fees, prepare documents early, verify websites, and use calculators to test repayments and deposit strategies.
Common documents that serve as proof of residence include utility bills, bank statements, rental agreements, or council rate notices. These documents must clearly display your name and address to be considered valid.
It's essential to ensure all documents are current, typically within the last three months, to avoid any questions regarding their validity. Lenders are more likely to approve applications that have recent and verifiable proof of residence.
If your address differs on your identification or if you've recently moved, it's important to update this information with all relevant institutions. Having mismatched addresses on your application documents can complicate the process or even lead to rejections.
To prevent such issues, take time to update your information with service providers and on your identification well in advance of applying. This attention to detail not only strengthens your application but also portrays you as an organized and responsible applicant.
Existing Financial Commitments
When applying for a caravan loan, transparency about your existing financial commitments is crucial. Lenders need a clear picture of your current financial obligations to assess your capacity to take on additional debt. Being upfront about any outstanding loans, credit card debts, or other financial liabilities can significantly impact the outcome of your application.
Types of documents that can help illustrate your financial obligations include current loan agreements, credit card statements, and personal loans. These documents provide lenders with insight into your monthly financial commitments and help them determine your debt-to-income ratio, a key metric in their decision-making process.
To effectively manage existing commitments while pursuing a new loan, consider strategies like consolidating debts to reduce the number of payments or negotiating lower interest rates on current debts. This approach not only eases monthly financial pressures but also presents you as a more reliable borrower to potential lenders.
For those with significant existing debts, developing a realistic repayment plan and sticking to it can improve your financial profile over time. Prioritizing high-interest debt reduction and minimizing additional credit usage are practical steps that can enhance your loan approval chances.
Ultimately, demonstrating financial responsibility through proactive debt management reflects positively on your loan application, showcasing your dedication to meeting all financial commitments, including potential new ones.
Down Payment Evidence
When seeking a caravan loan, proving your ability to make a down payment is a critical factor in the application process. A solid down payment demonstrates your financial commitment and reduces the lender's risk, often leading to more favourable loan terms.
Providing proof of your down payment capability is important as it assures lenders that you are financially prepared to invest in the caravan. It may also lower the total amount you need to borrow, reducing long-term interest costs.
Several forms of documentation can verify your down payment ability. These may include bank statements showing savings, a letter confirming a monetary gift from family, or documentation of any asset sales where funds were generated. The key is to provide clear, verifiable evidence that supports the amount you intend to contribute.
Accruing sufficient down payment funds can be challenging, but there are strategies to help save effectively. Consider setting up a dedicated savings account and automating regular deposits to build up your funds over time. Budgeting carefully to reduce unnecessary expenses and directing those savings towards your down payment can also make a significant difference.
Additionally, exploring ways to increase your income, like taking on side jobs or selling unused assets, can accelerate your savings goals. Proving robust down payment capability not only strengthens your loan application but also sets a solid financial foundation for your future caravan ownership.
Conclusion
As you embark on your caravan loan application journey, it's important to remember the essential documents that form the backbone of a successful application. From personal identification to proof of income and credit history, each piece plays a vital role in showcasing your financial profile to potential lenders.
Ensuring you have all necessary documents, such as proof of residence and evidence of a down payment, can significantly streamline the application process. Being thorough and organized not only reduces the likelihood of delays but also strengthens your credibility in the eyes of the lender.
To facilitate a smooth process, consider compiling a checklist of all required documents, and double-check that everything is up-to-date and accurately reflects your financial situation. If discrepancies arise, address them promptly to maintain the integrity of your application.
Finally, embrace the process with a spirit of preparedness and precision. By dedicating time to gather, review, and organize your documentation, you're not only enhancing your chances of securing the loan but also setting the stage for a seamless transition into caravan ownership.
Remember, a well-organized and comprehensive application reflects your commitment to financial responsibility and can make all the difference in achieving your dream of exploring the open road with the perfect caravan. Best of luck, and happy travels!
Published: Saturday, 16th Aug 2025
Author: Paige Estritori


No comments yet. Be the first to share your thoughts.